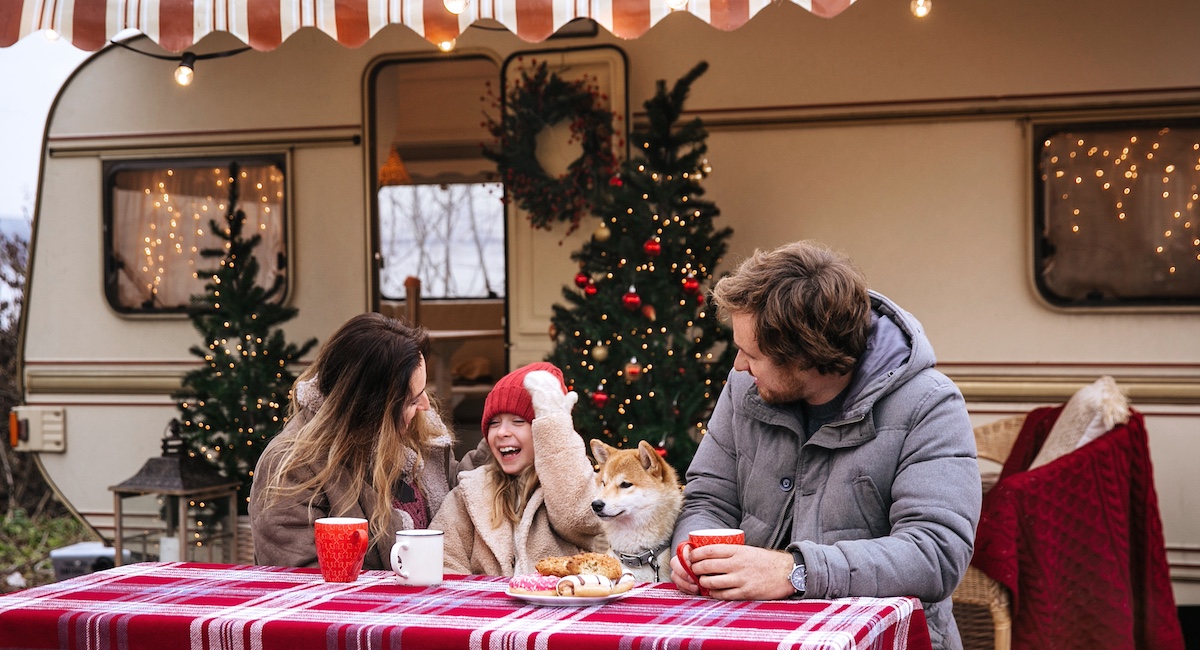
Using an RV only a few weekends a year feels like a loophole. It sits quietly in storage for months, minding its own business, collecting dust, and possibly hosting a family reunion for spiders. So it is fair to ask: do you really need RV insurance if you only use it a few times a year?
The practical answer is: usually, yes. The legal answer depends on what kind of RV you own, where it is registered, whether you financed it, and whether it has its own motor. The financial answer is even simpler: an RV can be expensive to repair, easy to damage, attractive to thieves, and surprisingly vulnerable even when parked. In other words, the risks do not take a vacation just because your RV does.
This guide explains when RV insurance is required, when it is optional, what part-time RV owners should consider, and how to avoid paying for coverage you do not need while still protecting your rolling vacation machine.
What Counts as an RV for Insurance Purposes?
Before deciding whether you need coverage, it helps to know what insurers mean by “RV.” Recreational vehicles generally fall into two big categories: motorized RVs and towable RVs.
Motorized RVs
Motorized RVs include Class A, Class B, and Class C motorhomes. These vehicles have engines and are driven like cars or trucks, although a Class A motorhome may feel more like piloting a studio apartment through a wind tunnel. Because they operate on public roads under their own power, they are usually treated like motor vehicles for insurance purposes.
Towable RVs
Towable RVs include travel trailers, fifth wheels, pop-up campers, toy haulers, and some truck campers. These do not drive themselves. They are pulled by another vehicle, usually a pickup or SUV. In many cases, liability coverage from the tow vehicle may extend to the trailer while it is attached and being pulled. However, that does not mean the trailer itself is fully protected.
This distinction matters because the insurance rules for a self-propelled motorhome are very different from those for a travel trailer that only moves when your truck says so.
Is RV Insurance Legally Required?
If your RV is motorized, you will generally need at least the minimum liability coverage required by your state. Liability insurance helps pay for injuries or property damage you cause to others in an accident. It does not repair your own RV, replace your belongings, or soothe your soul after backing into a campsite power pedestal.
State requirements vary, but the basic idea is consistent: if the RV drives on public roads under its own power, it usually needs insurance just like a car. Some states also have registration rules that require continuous insurance coverage while the vehicle has active plates, even if the vehicle is not being driven. That means canceling insurance during the off-season can create registration problems, fines, or reinstatement headaches.
For towable RVs, state law is usually more flexible. A travel trailer often does not need a separate liability policy because the liability coverage on the tow vehicle may apply while towing. Still, “not legally required” does not mean “financially smart to ignore.” A separate RV or trailer policy may cover physical damage, theft, storm damage, personal belongings, emergency expenses, and other risks your auto policy may not cover.
Does Occasional Use Change the Requirement?
Using your RV only a few times a year can affect your premium, but it does not magically erase legal or financial requirements. Insurance companies often ask how many days per year you use the RV because usage affects risk. A motorhome driven 15 days per year usually carries less road exposure than one driven across the country every month.
However, if the RV is registered, financed, or stored somewhere that requires proof of coverage, occasional use does not remove the need for insurance. Think of it like owning a boat, motorcycle, or classic car. The fact that it spends more time resting than roaming may reduce the risk, but the value of the asset is still sitting there.
Also, many RV claims happen when the RV is not actively being used. Hail can dent the roof. A tree branch can fall. A storage facility can flood. Rodents can chew wiring like they are judging an all-you-can-eat buffet. Theft, fire, vandalism, and weather do not check your camping schedule first.
When You Definitely Need RV Insurance
There are several situations where RV insurance is not just nice to have. It is either required or strongly recommended.
1. You Own a Motorhome
If your RV is self-powered, you generally need liability insurance to drive it legally. This applies whether you use it every weekend or only once a year for the big family trip where someone inevitably forgets the marshmallows.
2. You Have a Loan or Lease
If your RV is financed, your lender will usually require comprehensive and collision coverage. The reason is simple: until the loan is paid off, the lender has a financial interest in the RV. They want their collateral protected from accidents, theft, fire, storms, and other covered losses.
Canceling coverage on a financed RV can violate your loan agreement. In some cases, the lender may add force-placed insurance, which is often expensive and usually protects the lender more than it protects you.
3. Your RV Is Stored at a Facility
Some storage facilities require proof of insurance, especially if the RV is kept in a shared lot. Their insurance typically covers their business, not your individual RV. If another vehicle hits your camper, a storm damages the roof, or your personal items disappear, you may need your own policy to recover losses.
4. You Keep Valuable Gear Inside
Many RV owners store camping equipment, cookware, tools, electronics, bikes, portable grills, and outdoor furniture inside the RV. A homeowners or renters policy may offer limited coverage for personal property away from home, but limits and exclusions can apply. RV personal effects coverage can be useful if your camper doubles as a mobile gear closet.
5. You Camp in Public or Private Campgrounds
Even when parked, RVs can create liability risks. A guest could trip over your steps, a child could get hurt near your campsite setup, or your awning could damage a neighboring vehicle during a sudden wind gust. Vacation liability coverage can help when your RV is being used as a temporary residence at a campsite.
What Does RV Insurance Usually Cover?
RV insurance can be customized, but most policies are built from familiar coverage types. The right mix depends on your RV, your budget, and your risk tolerance.
Liability Coverage
Liability coverage helps pay for injuries or property damage you cause to others. For motorhomes, this is often the legally required foundation of the policy. For towable RVs, liability may be handled by the tow vehicle while connected, but you should confirm the details with your insurer.
Collision Coverage
Collision coverage helps repair or replace your RV if it is damaged in an accident, regardless of fault. This can matter even for careful drivers because RVs are large, heavy, and not exactly famous for nimble parking-lot ballet.
Comprehensive Coverage
Comprehensive coverage helps protect against non-collision losses such as theft, vandalism, fire, hail, falling objects, storms, and certain animal-related damage. For part-time RV owners, comprehensive coverage is often one of the most important protections because it applies to many risks that happen while the RV is parked or stored.
Uninsured and Underinsured Motorist Coverage
This coverage can help if another driver causes an accident and does not have enough insurance. Requirements and availability vary by state, but it is worth discussing if you drive a motorhome on public roads.
Personal Effects Coverage
Personal effects coverage can help protect items kept inside the RV, such as clothing, electronics, camping gear, and small appliances. This is especially helpful if your RV stays packed between trips. After all, unpacking the camper after every weekend trip is a noble idea that many people abandon by Monday morning.
Roadside Assistance
RV roadside assistance can cover towing, tire changes, battery help, fuel delivery, and lockout services. Standard auto roadside coverage may not be enough for a large motorhome or trailer, especially if specialized towing is needed.
Emergency Expense Coverage
If your RV becomes unusable during a covered trip, emergency expense coverage may help with lodging, transportation, or meals. This can turn a vacation disaster into a manageable inconvenience instead of a parking-lot tragedy starring you, a broken axle, and a bag of gas-station pretzels.
Vacation Liability Coverage
Vacation liability coverage applies when your RV is parked and being used as a temporary residence. It may help if someone is injured in or around your campsite and you are legally responsible.
Can You Pause RV Insurance During the Off-Season?
Many part-time RV owners ask whether they can simply cancel insurance when the RV is parked. In some cases, reducing coverage may make sense. Fully canceling the policy, however, can be risky.
If your motorhome is registered and plated, your state may require continuous coverage. If your RV is financed, your lender may require comprehensive and collision year-round. If it is stored, you may still want protection against theft, fire, vandalism, hail, wind, falling branches, flooding, and other non-driving losses.
A better option may be storage coverage, sometimes called laid-up coverage or comprehensive-only coverage. This type of adjustment may reduce or suspend road-related coverages while keeping protection for covered storage risks. Not every carrier offers the same option, and rules vary by state, so you should ask your insurer before making changes.
One important warning: do not drive the RV while road coverage is suspended. That is the insurance equivalent of wearing a raincoat with no sleeves. It may look like coverage, but it will disappoint you at exactly the wrong moment.
How Much Does RV Insurance Cost for Occasional Use?
RV insurance costs vary widely. A small travel trailer may cost much less to insure than a luxury Class A motorhome. Premiums are affected by location, driving record, RV type, value, usage, storage location, deductible, coverage limits, and optional add-ons.
Part-time use can sometimes help lower your premium because fewer days on the road may mean less accident exposure. Some insurers ask for estimated annual usage days, mileage, or whether the RV is used recreationally or as a full-time residence. Full-time RV living usually requires broader coverage because the RV functions more like a home.
Discounts may also help. Common possibilities include bundling RV insurance with auto or homeowners insurance, paying in full, having a clean driving record, completing safety courses, installing anti-theft devices, being the original owner, or storing the RV securely. Discount availability varies, so it pays to compare quotes.
What Happens If You Skip RV Insurance?
Skipping insurance can save money in the short term, but it can create expensive problems later. If you cause an accident in a motorhome without required liability coverage, you may face fines, license or registration consequences, lawsuits, and out-of-pocket repair bills. If your financed RV is uninsured, you may violate your loan agreement.
If your uninsured RV is damaged in storage, you may have no help paying for repairs. A hail-damaged roof, stolen catalytic converter, electrical fire, or water intrusion issue can cost thousands of dollars. RV repairs are not always cheap, and specialty parts can take time to source.
There is also the issue of coverage gaps. Some insurers may view a lapse in coverage as a risk factor, which can make future insurance more expensive or harder to obtain. Canceling and restarting every season may not save as much as expected once fees, administrative issues, and potential premium changes are considered.
Best Coverage Strategy for People Who Use an RV a Few Times a Year
If you are a weekend warrior or occasional traveler, you do not necessarily need the most expensive RV policy on the menu. You need a policy that matches how you actually use the RV.
For Motorhome Owners
Start with state-required liability coverage. Then consider collision and comprehensive coverage based on the RV’s value and your ability to pay for repairs yourself. If the RV is financed, comprehensive and collision are probably required. Add roadside assistance if you travel far from home or own a larger rig that would be costly to tow.
For Travel Trailer Owners
Confirm whether your tow vehicle liability coverage extends to the trailer while towing. Then consider a separate trailer policy for physical damage, theft, personal effects, and campsite liability. If you financed the trailer, expect the lender to require comprehensive and collision coverage.
For Stored RVs
Ask about storage coverage or reducing certain coverages during the off-season. Keep comprehensive coverage if the RV has meaningful value or is exposed to weather, theft, vandalism, fire, falling objects, or pests. Review storage facility rules and your loan agreement before making changes.
For Owners Who Keep the RV Packed
Make an inventory of items stored in the RV. Estimate the replacement cost of electronics, tools, bedding, cooking gear, outdoor furniture, and recreational equipment. Then compare that number with your personal effects coverage limit.
Questions to Ask Before Buying or Reducing RV Insurance
Before choosing coverage, ask yourself a few practical questions:
- Is my RV motorized or towable?
- Is the RV financed or leased?
- Does my state require continuous coverage while it is registered?
- Does my storage facility require proof of insurance?
- Would I be comfortable paying for a total loss out of pocket?
- Does my tow vehicle policy cover liability while towing?
- Are my belongings inside the RV covered?
- Do I need roadside assistance that can handle an RV?
- Do I use the RV as a temporary residence at campgrounds?
- Can I reduce coverage during storage instead of canceling it?
These questions can prevent both overpaying and underinsuring. The goal is not to buy every coverage available. The goal is to avoid the dreaded “I thought that was covered” conversation after something goes wrong.
Real-Life Examples for Occasional RV Owners
Example 1: The Twice-a-Year Motorhome
Suppose you own a Class C motorhome and use it for one summer trip and one fall camping weekend. Even with low mileage, it is still a motor vehicle. You likely need liability coverage to drive legally. If the motorhome is worth $60,000 and you cannot comfortably replace it, comprehensive and collision coverage may also make sense.
Example 2: The Paid-Off Travel Trailer
You own a paid-off travel trailer and tow it with an insured pickup. Your truck’s liability coverage may apply while towing, but the trailer itself may not be covered for hail, theft, fire, or collision damage unless you buy separate coverage. If the trailer is older and low in value, you may choose a modest policy or higher deductible. If it is newer, separate coverage is usually worth considering.
Example 3: The Stored Fifth Wheel
Your fifth wheel sits in an outdoor storage lot for ten months a year. You rarely tow it, but it is exposed to wind, hail, theft, water damage, and vandalism. In this case, storage-focused comprehensive coverage may be more important than road coverage during the off-season.
Experiences and Practical Lessons From Part-Time RV Ownership
Many occasional RV owners start with the same assumption: “We barely use it, so the risk must be tiny.” That sounds logical until you remember that RV ownership is not only about driving. It is also about storage, weather, maintenance, campsite liability, and the mysterious ability of small problems to become large invoices.
One common experience is the surprise storage claim. An RV owner parks a travel trailer behind the house for winter, thinking the safest place is the driveway. Then a heavy storm drops a branch on the roof. The trailer was not moving. Nobody was camping. No one was even inside pretending to organize the storage bins. Yet the damage was real, and roof repairs were expensive. This is where comprehensive coverage can earn its keep.
Another frequent lesson involves personal belongings. Part-time RVers often keep the camper stocked so it is ready to go. That means dishes, bedding, tools, chairs, leveling blocks, outdoor rugs, fishing gear, portable speakers, and sometimes a small TV are left inside. It feels efficient until theft or water damage occurs. Without enough personal effects coverage, replacing those items can become a frustrating out-of-pocket expense.
There is also the “short trip, big problem” scenario. A family takes their motorhome out for the first time in eight months. The campground is only 90 miles away, so they assume not much can happen. Then a tire fails, causing damage to the wheel well and side panel. The trip was short, but the repair bill was not. Occasional use lowers exposure, but it does not eliminate the possibility of an accident or mechanical-related damage.
Part-time RV owners also learn that towing is not the same as driving a normal car. Even careful drivers can clip a gas station post, misjudge a campsite turn, or discover that backing a trailer is a team-building exercise disguised as a marital stress test. Collision coverage can matter most when the accident is embarrassing but still expensive.
Another practical experience comes from campgrounds. When your RV is parked and being used as a temporary home, your risks change. You are no longer just a driver. You are a campsite host, chef, extension-cord manager, awning supervisor, and unofficial safety officer. If a guest trips on your steps or your equipment damages someone else’s property, vacation liability coverage may help.
Owners who finance an RV often discover that they have less flexibility than expected. They may want to cancel insurance during the off-season, only to learn that the lender requires year-round comprehensive and collision coverage. In that situation, the better move is usually to ask about deductible adjustments, discounts, bundling, or storage options rather than canceling the policy.
Finally, many occasional RVers find peace of mind valuable. RV trips are supposed to feel freeing, not financially terrifying. The right insurance policy does not need to be fancy, but it should match the real risks: road accidents, storm damage, theft, stored belongings, towing needs, and liability. When coverage is chosen carefully, you can spend less time worrying about worst-case scenarios and more time debating important camping issues, such as whether hot dogs count as dinner three nights in a row.
Conclusion: So, Do You Need RV Insurance If You Barely Use It?
If you own a motorhome, you probably need RV insurance even if you only use it a few times a year. If you own a towable RV, separate insurance may not always be legally required, but it can still be financially wise. Lenders, storage facilities, state registration rules, and your own risk tolerance all matter.
The smartest approach is not to ask, “How little insurance can I get away with?” A better question is, “What could go wrong while my RV is driven, parked, stored, or used as a temporary home?” Once you answer that, the right coverage becomes much clearer.
For occasional RV use, consider a flexible policy with liability where required, comprehensive coverage for storage risks, collision coverage if the RV has significant value, personal effects coverage if you keep belongings inside, and roadside assistance if towing would be costly. Ask your insurer about seasonal or storage options before canceling coverage outright.
Your RV may only come out a few times a year, but when it does, it carries your vacation plans, your gear, your family, and possibly your entire snack supply. Protecting it is not overkill. It is good planning with cup holders.
SEO Tags
Note: Insurance laws, lender rules, coverage options, and discounts vary by state, insurer, RV type, and policy language. Always confirm requirements with your insurance agent, state motor vehicle agency, storage facility, and lender before reducing or canceling coverage.