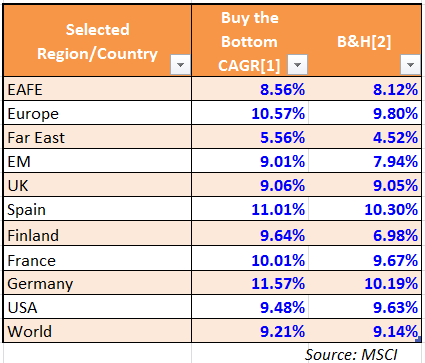
Note: This article is for educational and informational purposes only. It is not personal financial advice, and readers should consider their own goals, risk tolerance, time horizon, and professional guidance before making investment decisions.
Every investor has had the same little fantasy: “What if I only bought stocks near market bottoms?” It sounds deliciously simple. Wait for fear, grab bargains, look wise at dinner parties, and retire with the smug glow of someone who “knew it all along.” In this fantasy, the investor strolls into the market at the exact moment everyone else is panicking, buys the dip with cinematic confidence, and exits the scene as violins play softly in the background.
Unfortunately, the real stock market does not hand out neatly labeled signs saying, “Congratulations, this is the bottom.” Market bottoms usually arrive dressed as bad news, ugly headlines, falling account balances, and a general feeling that perhaps stuffing cash under a mattress was an underrated strategy. That is what makes the question so interesting. What would happen if you only bought near market bottoms? Would you become a investing legend, or would you spend years sitting on cash while the market ran away without you?
The honest answer is both inspiring and annoying: buying near market bottoms can be powerful, but waiting only for bottoms is usually a difficult, stressful, and often underperforming strategy. The market rewards courage during downturns, but it also rewards consistency, patience, and time in the market. In other words, the perfect investor buys the bottom. The practical investor builds a plan that works even when the bottom is hiding under a pile of scary headlines.
Why Buying Near Market Bottoms Sounds So Attractive
Buying low is one half of the oldest investing advice in the world: buy low, sell high. It is so simple that it sounds like something printed on a mug in a financial advisor’s office. The appeal is obvious. If you buy after stocks have already fallen 20%, 30%, or even 40%, you are purchasing future earnings at lower prices. Your expected long-term return may improve because you are not paying peak optimism prices.
Historically, major stock market declines have often created excellent long-term buying opportunities. After the 2008 financial crisis, investors who bought broad U.S. stock indexes during the panic and stayed invested for years were rewarded handsomely. During the COVID-19 crash in early 2020, the market fell with terrifying speed, but the rebound also came faster than many people expected. Investors who had cash, discipline, and a strong stomach could buy quality assets at temporarily depressed prices.
That is the magic of buying near market bottoms. You are buying when pessimism is already reflected in prices. You are not chasing the crowd at the top of the roller coaster. You are buying when everyone else is asking whether the roller coaster has been inspected recently.
The Big Problem: You Only Know the Bottom Later
The market bottom is easy to identify in hindsight. On a historical chart, it looks like a clean turning point. In real life, it feels like stepping onto a frozen lake while people on television debate whether the lake is actually made of pudding.
Near the bottom, the news is usually terrible. Earnings estimates may be falling. Economic data may be weakening. Unemployment may be rising. Banks, households, companies, or governments may be under stress. Social media may sound like a financial horror movie written by people who have had too much coffee.
That is why so few investors buy aggressively near market lows. The exact moment when expected future returns may be improving is often the same moment when emotional comfort is collapsing. You do not get bargain prices because the world feels calm. You get bargain prices because investors are demanding a discount for uncertainty.
Bottoms Are Not Bells; They Are Blurs
Market bottoms rarely happen as one clean event. They often include false starts, sharp rallies, renewed selloffs, and confusing reversals. A market can fall 15%, bounce 8%, fall another 10%, rally again, and still not reveal whether the worst is over. Trying to wait for the “real” bottom can become a mental trap. By the time the recovery looks obvious, prices may already be much higher.
This is why professional investors often talk about buying “near” bottoms rather than “at” bottoms. The difference matters. Buying at the exact bottom is mostly luck. Buying near a bottom can be the result of discipline, valuation awareness, cash management, and a willingness to accept short-term discomfort.
What the Data Suggests About Waiting for Perfect Timing
Market timing studies tend to arrive at a similar conclusion: perfect timing is wonderful in theory, but extremely difficult in practice. Charles Schwab has published research comparing different investors who put money to work at different times. The perfect timer did best, as expected. But the investor who simply invested immediately often came surprisingly close, while the investor who waited in cash for the perfect moment fell behind.
That finding is important because it challenges the fantasy of endless patience. Sitting in cash feels safe, but it has an opportunity cost. Markets rise more often than they fall over long periods. If an investor waits years for a major crash, they may miss dividends, compounding, and price appreciation along the way. Waiting for the perfect sale can become expensive if the store keeps raising prices before the sale begins.
There is another issue: many of the market’s best days occur close to its worst days. That makes tactical exits dangerous. If an investor sells during a downturn hoping to buy lower, they must make two correct decisions: when to exit and when to re-enter. Missing only a handful of strong rebound days can dramatically reduce long-term returns. The market’s best days often do not send calendar invites.
The Emotional Math of Buying Near Bottoms
Let’s imagine two investors. Investor A contributes steadily every month to a diversified portfolio. Investor B keeps cash aside and waits for major market declines. Investor B may occasionally feel brilliant when stocks fall. But during long bull markets, Investor B may feel frustrated, impatient, or pressured to buy after prices have already risen.
Now imagine a crash finally arrives. Investor B has the cash. Great! But now comes the hard part. Does Investor B buy after a 15% decline? What if the market falls 30%? Does Investor B buy after a 30% decline? What if the headlines suggest a recession, layoffs, bank stress, or geopolitical chaos? Suddenly the strategy that looked smart in a spreadsheet feels like catching a falling safe.
This is where behavioral finance matters. Investors are not calculators with brokerage accounts. They are humans with fear, regret, pride, bills, families, and group chats full of dramatic predictions. A strategy only works if you can actually follow it when your emotions are yelling.
What “Near Market Bottoms” Really Means
To make this idea practical, investors need a definition. “Near market bottoms” could mean buying after a 10% correction, a 20% bear market, a valuation reset, a recession scare, or a volatility spike. Each definition creates a different strategy.
Buying After a 10% Correction
A 10% decline is common. Corrections can happen even during healthy bull markets. Buying after corrections can be a reasonable way to add capital when prices are less expensive than they were recently. The challenge is that not every 10% decline becomes a major bottom. Sometimes it is just the opening act.
Buying After a 20% Bear Market
A 20% decline is more serious. Bear markets are painful but historically normal parts of long-term investing. Buying after a broad market decline of 20% or more has often improved future return potential. But bear markets can continue much lower, and recovery can take months or years. Investors using this approach need patience and emotional durability.
Buying Based on Valuation
Some investors define opportunity using valuation measures such as price-to-earnings ratios, dividend yields, or expected returns. This can be more thoughtful than simply watching price declines. However, valuation is not a timing tool with perfect accuracy. Expensive markets can become more expensive, and cheap markets can remain cheap long enough to make everyone question their life choices.
Why Dollar-Cost Averaging Often Beats Waiting Emotionally
Dollar-cost averaging means investing a fixed amount at regular intervals, regardless of whether the market is up, down, cheerful, grumpy, or acting like it drank three energy drinks. This strategy does not promise the highest possible return. Instead, it reduces timing pressure.
For many investors, that is the key. Dollar-cost averaging turns investing from a dramatic prediction contest into a habit. You buy more shares when prices are lower and fewer shares when prices are higher. Over time, the process can help investors stay involved without trying to guess every twist in the market.
Does dollar-cost averaging always beat lump-sum investing? No. Because markets have historically trended upward over long periods, investing a lump sum earlier often has a mathematical advantage. But dollar-cost averaging can be psychologically superior for investors who might otherwise freeze, overthink, or panic. The best strategy is not just the one that looks good in a backtest. It is the one you can stick with when your portfolio is wearing a tiny storm cloud as a hat.
A Better Version of the Bottom-Buying Strategy
The smartest approach may not be “only buy near market bottoms.” A more practical version is: invest regularly, stay diversified, and keep a rules-based plan for adding more during major declines.
For example, an investor might contribute monthly to a broad index fund and also maintain a modest cash reserve for opportunistic buying. The investor could create rules such as:
- Add an extra amount after the market falls 10% from its recent high.
- Add a larger amount after a 20% decline.
- Rebalance back to target allocation when stocks fall sharply.
- Never use emergency savings for market buying.
- Never abandon diversification to chase a single “cheap” stock.
This framework combines discipline with flexibility. It allows the investor to benefit from downturns without turning the entire financial plan into a guessing game. It also avoids the biggest weakness of pure market timing: sitting out the market for too long.
Specific Example: The Investor Who Waits Too Long
Suppose an investor has $50,000 ready to invest. They believe a market crash is coming, so they wait. The market rises 15% in year one, 12% in year two, and 8% in year three. Finally, in year four, the market drops 20%. The investor feels vindicated and buys.
But here is the awkward math: even after that 20% decline, the market may still be higher than where it was when the investor first decided to wait. In that case, buying the “bottom” was not better than investing earlier. It only felt better because the investor got to buy after a decline.
This happens more often than people expect. A large decline after a large advance may still leave prices above previous levels. That is why waiting for a crash can be dangerous. The market does not care about your entry-point wishlist. It has its own schedule, and it refuses to sync with your budgeting app.
When Buying Near Bottoms Can Work Well
Buying near market bottoms can work especially well for investors who already have a long-term plan. The key is preparation. If you decide what to do before the decline happens, you are less likely to make emotional decisions during the decline.
This works best when investors use broad diversification, avoid leverage, keep enough cash for real-life needs, and understand that prices may keep falling after they buy. The goal is not to win the exact bottom. The goal is to buy good assets at reasonable or attractive prices and hold them long enough for business value and economic growth to matter.
Good Bottom-Buying Requires Humility
The best investors are rarely the loudest bottom-callers. They are usually humble about uncertainty. They know that a 25% decline can become a 35% decline. They know that scary markets can get scarier. They also know that long-term opportunity often appears when short-term confidence is low.
Humility leads to better tactics. Instead of going all-in at once, an investor might buy in stages. Instead of betting everything on one sector, they might use diversified funds. Instead of relying on predictions, they might use rebalancing rules. The result is a strategy that respects uncertainty while still taking advantage of lower prices.
Risks of Only Buying Near Market Bottoms
The first risk is underinvestment. If you only buy when markets crash, you may spend most of your life waiting. Long bull markets can last for years. During those years, companies earn profits, pay dividends, buy back shares, innovate, expand, and create value. Sitting completely outside the market means missing that compounding engine.
The second risk is hesitation. Investors who wait for bottoms often discover that when a bottom-like moment arrives, they want an even lower price. A 20% decline makes them wait for 30%. A 30% decline makes them wait for 40%. Then the market rebounds, and they wait for a retest that never comes. This is how a “disciplined cash strategy” quietly turns into a “watching the train leave the station strategy.”
The third risk is concentration. Some investors try to buy the most beaten-down stocks near market bottoms. That can produce big gains, but it can also lead to value traps. A stock that is down 70% is not automatically cheap. Sometimes it is a bargain. Sometimes it is a warning label with a ticker symbol.
What Long-Term Investors Should Focus On Instead
Rather than obsessing over exact bottoms, long-term investors may be better served by focusing on five durable principles: time horizon, diversification, regular contributions, rebalancing, and behavior.
Time horizon matters because stocks are volatile in the short term but have historically rewarded patient investors over longer periods. Diversification matters because no one knows which sector, country, or company will lead next. Regular contributions matter because they automate discipline. Rebalancing matters because it forces investors to trim what has grown and add to what has lagged. Behavior matters because a good plan ruined by panic is just a bad plan with nicer stationery.
Buying near market bottoms can be part of this system, but it should not replace the system. A portfolio should not depend on heroic timing. It should be built to survive imperfect timing.
Personal Experience-Style Lessons: What It Feels Like to Buy Near Market Bottoms
Anyone who has invested through a real downturn knows that buying near market bottoms sounds easier in articles than it feels in real life. On paper, the plan is elegant: wait for fear, buy quality assets, and let time do the heavy lifting. In practice, your screen is red, experts disagree, headlines are dramatic, and your brain starts whispering, “Maybe this time is different.” Your brain is very creative during drawdowns. Not always helpful, but definitely creative.
One useful experience is learning that confidence rarely arrives before prices recover. Many investors expect to feel brave before they buy. But near a bottom, confidence is usually absent. The better approach is to rely on pre-made rules. For example, an investor who decided in advance to add money at every 10% market decline does not need to wake up feeling like Warren Buffett in a superhero cape. They only need to follow the rule.
Another practical lesson is that buying in pieces can reduce regret. If you invest all your extra cash after a 20% decline and the market falls another 15%, you may feel foolish, even if the decision is reasonable long term. If you divide the money into several planned purchases, you give yourself room to act if prices fall further. This does not maximize returns if the first purchase marks the bottom, but it can make the strategy easier to follow emotionally.
It also helps to keep a written investment checklist. Before buying during a decline, ask: Is my emergency fund intact? Is my time horizon still long? Am I buying a diversified asset or gambling on one damaged company? Am I using money I can leave invested for years? If the answers are healthy, the purchase is more likely to be a disciplined investment rather than a panic-flavored impulse buy.
One of the biggest experiences investors report after downturns is regretbut regret comes in two flavors. Some regret buying too early. Others regret not buying at all. The second kind can be more painful because it often comes from waiting for perfect certainty. Markets rarely offer certainty at attractive prices. By the time the outlook feels comfortable, the discount may be gone.
A final experience is that downturns reveal whether your portfolio matches your personality. If a 20% decline makes you want to sell everything and become a professional blanket fort architect, your allocation may be too aggressive. The best portfolio is not the one that impresses strangers online. It is the one you can hold through ugly markets without blowing up your plan.
So, what if you only bought near market bottoms? If you could do it consistently, you would probably achieve excellent returns. But if trying to do it caused you to sit in cash too long, miss rebounds, or freeze during scary moments, the strategy could backfire. A better lesson is this: welcome market declines as opportunities, but do not build your entire plan around predicting them. Invest regularly, prepare for volatility, keep some flexibility, and remember that the market does not need to be perfectly timed to be powerfully rewarding over time.
Conclusion
Buying near market bottoms is one of the most attractive ideas in investing because it combines logic, courage, and the thrill of getting a deal. Lower prices can improve future return potential, especially for diversified investors with long time horizons. But the strategy has a major flaw: bottoms are only obvious after the fact.
For most investors, the better question is not “How do I buy the exact bottom?” It is “How do I build a plan that lets me keep investing when prices are lower?” That shift turns market volatility from a prediction contest into a preparation exercise. The winners are not always the people who call the bottom. More often, they are the people who stay invested, keep contributing, rebalance when needed, and avoid letting fear take the steering wheel.
In the end, buying near market bottoms can help. But consistently investing through market cycles may help even more. The market rewards patience, discipline, and humility. It rarely rewards waiting forever with cash in hand and a perfect-bottom detector that, sadly, never came with batteries.