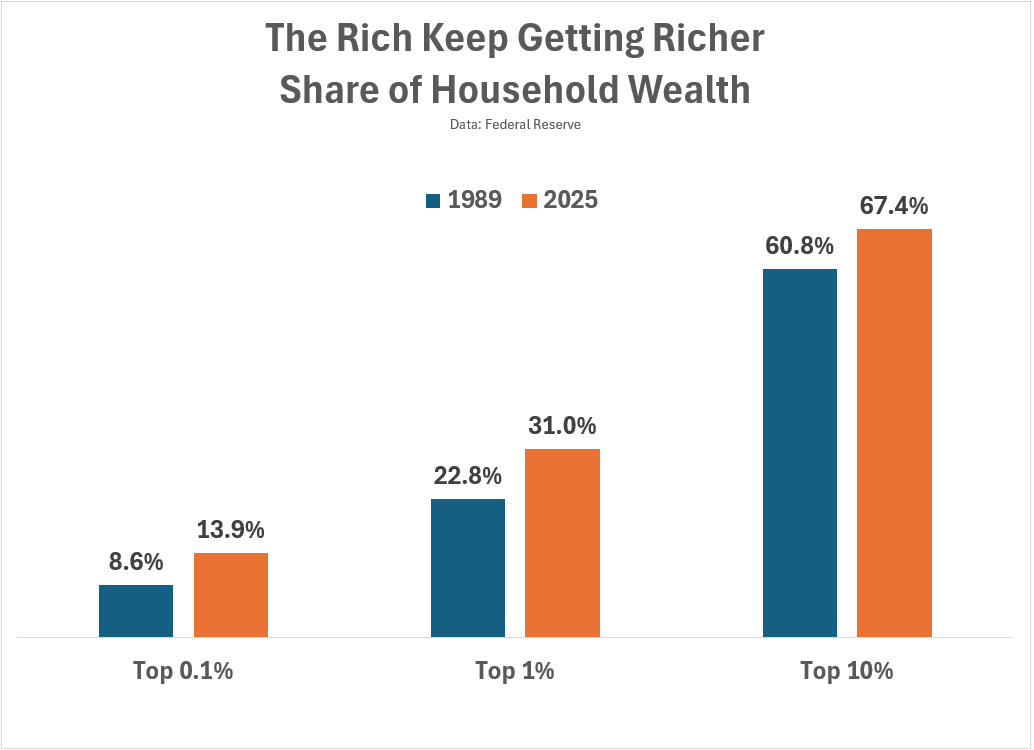
You got the raise. You paid off a bill. You upgraded from “ramen with optimism” to “salmon with a side salad.” On paper, your financial life may look better than it did five years ago. So why don’t you feel rich?
The answer is not simply that you need more money, although your grocery receipt may strongly disagree. The feeling of wealth is shaped by income, expenses, debt, savings, housing costs, social comparison, inflation, expectations, and the sneaky little raccoon known as lifestyle creep. Being rich is partly math, partly psychology, and partly whether your car makes a new noise every time you turn left.
In the United States, many people earn more than they used to but feel less secure than they expected. Median household income has risen in nominal terms, yet major expenses such as housing, transportation, food, insurance, health care, child care, and education continue to swallow a huge share of monthly cash flow. That means a household can look successful from the outside while feeling financially squeezed on the inside.
This article explains why you don’t feel rich, even if your income has improved, and what you can do to feel more financially grounded without moving into a cave and calling it “minimalism.”
The Definition of “Rich” Keeps Moving
One reason you don’t feel rich is that the finish line keeps jogging away from you in designer sneakers. Americans often say they need a surprisingly high net worth to be considered wealthy. Recent wealth surveys have found that many people believe it takes millions of dollars to be truly rich, while many also say they need six-figure income just to feel financially comfortable.
That gap matters. If your personal definition of rich is “never worrying about money again,” then even a solid salary may not create the emotional payoff you expected. You may be doing better than average, but your brain is comparing your life to an imaginary version of wealth where bills arrive, look at your bank balance, apologize politely, and leave.
Income Is Not the Same as Wealth
Income is what comes in. Wealth is what stays. A high-income household can feel broke if every dollar is already assigned to a mortgage, car payments, student loans, credit cards, subscriptions, private school, aging parents, travel expectations, and the mysterious “miscellaneous” category that somehow includes $87 worth of things from Target.
Net worth gives a clearer picture than salary alone. It includes assets such as savings, investments, retirement accounts, home equity, and business ownership, minus liabilities such as mortgages, credit card balances, student loans, auto loans, and personal debt. A person making $90,000 with low debt and strong savings may be more financially secure than someone making $250,000 but spending $252,000 with confidence and a rewards card.
Inflation Made Normal Life Feel Premium
Inflation is one of the biggest reasons people do not feel rich. When prices rise quickly, your income may increase, but your purchasing power can still feel like it took a nap in traffic. Groceries, rent, insurance, utilities, restaurant meals, car repairs, and household basics have all become more expensive in recent years.
The frustrating part is that inflation does not always feel dramatic in one purchase. It shows up as a slow leak. The cereal is smaller. The bill is higher. The “affordable” lunch now costs what dinner used to cost. Suddenly, you are standing in a grocery aisle doing advanced emotional math over a carton of eggs.
Even when inflation cools, prices usually do not go back to where they were. Slower inflation means prices are rising less quickly, not that your favorite burrito will return to its 2018 price and send you a handwritten apology.
Your Fixed Costs May Be Too Heavy
Feeling rich depends less on your gross income and more on your breathing room. If fixed costs are high, your money feels trapped before the month even begins.
Housing and transportation are often the biggest budget anchors. In many U.S. households, these two categories alone take up a large share of annual spending. Add health care, food, insurance, debt payments, taxes, child care, and retirement contributions, and even a strong income can feel strangely fragile.
The “Good Life” Got Expensive
A middle-class lifestyle once felt easier to define: a home, a reliable car, occasional vacations, health insurance, retirement savings, and maybe a child who does not treat the refrigerator like a 24-hour buffet. Today, those same basics can feel like luxury items in many cities.
Homeownership is a major example. Higher home prices, mortgage rates, property taxes, repairs, insurance premiums, and maintenance costs can make owning a home feel less like a victory lap and more like adopting a very expensive wooden pet. Renting is not automatically easy either, especially in high-cost metro areas where rent can consume a painful share of take-home pay.
Lifestyle Creep Is Quiet but Very Talented
Lifestyle creep, also called lifestyle inflation, happens when spending rises as income rises. It rarely feels reckless. In fact, it often feels reasonable. You worked hard, so you upgrade the apartment. You are busy, so you order delivery. You got promoted, so you replace the car. You survived a brutal week, so the cart says “treat yourself” and suddenly you own a countertop appliance that makes one specific kind of waffle.
The problem is not enjoying your money. The problem is when every raise gets absorbed into a more expensive version of normal. Once a luxury becomes routine, cutting back feels like deprivation, even if you were perfectly happy before.
The Raise Rule Can Help
A simple way to fight lifestyle creep is to create a raise rule before the money arrives. For example, you might save or invest 50% of every raise, use 30% for debt reduction or future goals, and enjoy 20% guilt-free. The exact percentages can vary, but the principle is powerful: decide in advance, because your future self has excellent taste and terrible impulse control.
Debt Makes Income Feel Smaller
Debt is another major reason people do not feel rich. Credit card balances, student loans, auto loans, medical debt, personal loans, and buy-now-pay-later plans can quietly reduce financial flexibility. Even if the monthly payment seems manageable, the emotional weight can be heavy.
Credit card debt is especially expensive because high interest rates make balances harder to eliminate. A purchase that felt small at the time can become a long-term roommate with terrible manners. When debt payments eat up cash flow, you may technically earn a good income but still feel like your paycheck is wearing roller skates.
Minimum Payments Can Create Maximum Frustration
Minimum payments are designed to keep an account current, not to make you feel free. Paying only the minimum can stretch repayment over years and increase total interest. That is why debt payoff strategies such as the avalanche method, which targets highest-interest debt first, or the snowball method, which targets smallest balances first, can help restore a sense of progress.
Social Comparison Is a Budget Killer
You may not feel rich because you are comparing your behind-the-scenes finances to someone else’s highlight reel. Social media is basically a museum of vacations, renovations, engagement rings, new cars, glowing skin, and suspiciously calm toddlers. It rarely shows the credit card statement, the family help, the debt, the panic, or the 2 a.m. spreadsheet titled “Can We Afford This???”
Comparison changes your reference point. A perfectly good home can feel small after scrolling through dream kitchens. A reliable car can feel embarrassing next to luxury SUVs. A comfortable vacation can feel inadequate if someone else is posting from a private overwater bungalow while you are trying to find the hotel ice machine.
Your Neighbor’s Lifestyle Is Not Your Financial Plan
The wealth you see is not always wealth. Sometimes it is debt. Sometimes it is family money. Sometimes it is a business expense. Sometimes it is a one-time splurge. And sometimes it is just a carefully cropped photo hiding a sink full of dishes and three overdue bills.
A healthier question is not “Why don’t I have what they have?” but “Does my spending match my values, goals, and actual bank account?” That question is less glamorous, but it has never accidentally financed a boat.
You May Be Underestimating Financial Security
Many people think being rich means having more: more income, more stuff, more travel, more upgrades, more options. But financial security often feels less flashy. It looks like an emergency fund, low-interest debt, consistent investing, adequate insurance, retirement contributions, and the ability to handle a surprise expense without turning into a haunted Victorian ghost.
Financial security is not always exciting. Nobody throws a party because they increased their 401(k) contribution by 2%. There is no confetti cannon for having three months of emergency savings. But these quiet moves often create more lasting peace than another lifestyle upgrade.
Liquidity Matters More Than Looks
You can own impressive assets and still feel financially stressed if you do not have accessible cash. This is the classic “house rich, cash poor” problem. Your net worth may look good, but if your money is locked in home equity, retirement accounts, or illiquid investments, a sudden car repair can still feel like a personal attack.
That is why emergency savings matter. Cash may not be glamorous, but it is emotionally powerful. It turns crises into inconveniences. It lets you make decisions without panic. It gives your nervous system a tiny financial weighted blanket.
Your Goals May Be Bigger Than Your System
Sometimes you do not feel rich because your goals are real, important, and expensive. Retirement, homeownership, raising children, caring for parents, starting a business, changing careers, paying for college, traveling, and building wealth all require planning. If you have big goals but no clear system, money can feel chaotic even when you are earning enough.
A financial system does not need to be complicated. In fact, the best systems are boring enough to survive real life. Automate savings. Automate investments. Track major spending categories. Review subscriptions. Create sinking funds for predictable expenses. Keep debt payoff visible. Revisit goals quarterly. Basically, make your money less dependent on heroic willpower, because heroic willpower tends to disappear around online sales and cheese boards.
The Psychology of “Enough” Is Hard
Humans adapt quickly. This is called hedonic adaptation: the new thing becomes normal. The first month with a higher salary feels amazing. Six months later, it feels ordinary. The bigger apartment becomes home. The nicer car becomes transportation. The upgraded phone becomes the thing you drop on your face in bed.
This does not mean money cannot improve happiness. Money can reduce stress, increase options, buy time, improve health access, and create safety. But after basic needs and reasonable comforts are covered, more money does not automatically create more peace. Without a definition of enough, every financial milestone becomes a waiting room for the next one.
Define Rich in Human Terms
Instead of defining rich only as a number, define it by what money should do for your life. Rich might mean sleeping well because bills are covered. It might mean helping family without resentment. It might mean working fewer hours, taking a real vacation, changing jobs, funding retirement, or having time to cook dinner with people you love.
Numbers matter, but they need a job. A million dollars sounds impressive, but the real question is what it buys: freedom, security, time, generosity, flexibility, or peace. Without that clarity, money becomes a scoreboard with no final whistle.
How to Start Feeling Richer Without Winning the Lottery
You do not need to become a billionaire or start wearing sunglasses indoors to feel richer. You need more alignment between your money, expectations, and daily life.
1. Calculate Your Real Financial Breathing Room
Look beyond salary. Calculate take-home pay minus fixed costs, debt payments, savings, and essential expenses. This number shows your real flexibility. If it is small, the problem may not be your attitude; it may be that your fixed costs are too high.
2. Build a Cash Buffer
Even a small emergency fund can reduce stress. Start with a starter goal, then work toward one to three months of essential expenses, and eventually more if your income is variable or your household depends on one earner.
3. Audit Lifestyle Creep
Review the expenses that quietly became normal: delivery, subscriptions, upgrades, memberships, convenience fees, premium services, and impulse purchases. Keep what genuinely improves your life. Cut what only creates background noise with a monthly charge.
4. Pay Down High-Interest Debt
High-interest debt is one of the fastest ways to feel financially stuck. Pick a payoff method and make progress visible. Every balance you reduce gives future income more room to breathe.
5. Stop Letting Social Media Set Your Budget
Mute accounts that make you feel behind. Follow people who talk honestly about money, patience, trade-offs, and long-term planning. Your financial life does not need to be photogenic to be successful.
6. Buy Back Time When Possible
Research on money and happiness often points to the value of time. If you can afford it, spending money to reduce stress, save time, or remove disliked tasks may create more happiness than buying another object.
7. Create Your Own Wealth Scorecard
Track numbers that matter: net worth, emergency savings, debt balances, savings rate, retirement contributions, and days of expenses covered by cash. These measures are more useful than comparing your life to someone else’s vacation photos.
Personal Experiences: Why Feeling Rich Often Comes Late
Many people do not feel rich during the actual process of becoming financially stronger. That sounds strange, but it makes sense. Building wealth often feels like sacrifice before it feels like freedom.
Think about the person who finally earns a better salary after years of hard work. At first, the new income feels exciting. Then reality arrives with a clipboard. The car needs tires. Rent increases. Health insurance premiums rise. A family member needs help. Student loans restart. Groceries cost more. The raise disappears into responsible adult categories, which are important but not exactly thrilling. Nobody says, “Wow, I feel so wealthy because I bought a sensible amount of paper towels.”
Another common experience is the delayed reward of saving. Putting money into retirement accounts can feel invisible. You do not see a nicer living room. You do not taste a better dinner. You simply watch money leave your checking account and go into a future version of you who, frankly, could at least send a thank-you card. But over time, those quiet transfers become real wealth. The problem is that the emotional payoff is slow, while the pleasure of spending is immediate.
Families often experience this tension even more strongly. A household may earn what once sounded like a dream income, but after mortgage payments, child care, school expenses, insurance, groceries, utilities, car costs, and retirement savings, the month can still feel tight. From the outside, they look comfortable. Inside, they are negotiating whether the family vacation should be “beach hotel” or “visit relatives and call it cultural enrichment.”
There is also the emotional effect of growing expectations. When you were younger, a full refrigerator, a reliable phone, and a little weekend money may have felt luxurious. Later, your expectations expand. You want a safer neighborhood, better health care, stronger retirement savings, better schools, more travel, higher-quality food, and maybe a couch that does not make guests question your life choices. These are not foolish desires. They are normal. But they make “enough” more complicated.
Some people only realize they were doing well when they look backward. They remember the years when an unexpected bill caused panic, when debt felt endless, or when payday could not arrive fast enough. Later, even if they do not feel rich, they notice something important: emergencies no longer destroy the month. They can say no to a bad job. They can help someone. They can repair the car without financial drama. That is wealth, even if it does not come with a yacht or a dramatic movie soundtrack.
The lesson is simple: feeling rich is not always about having a huge income. It is about having margin. It is about owning your time, reducing panic, making choices from values instead of fear, and knowing where your money is going. Rich is not just the ability to buy more. Sometimes rich is the ability to need less, choose better, sleep deeper, and stop measuring your life against people whose finances you cannot actually see.
Conclusion: You May Be Richer Than You Feel
If you do not feel rich, you are not alone. Many Americans feel financially stretched because the cost of normal life has increased, debt is common, housing is expensive, and social comparison is everywhere. At the same time, your feeling of wealth may lag behind your actual progress because savings, debt reduction, and long-term investing do not always feel exciting in the moment.
The goal is not to trick yourself into feeling wealthy while ignoring real financial problems. The goal is to understand the difference between income and wealth, comfort and appearance, spending and security. When you lower unnecessary fixed costs, reduce high-interest debt, build cash savings, invest consistently, and define enough for yourself, you begin to feel richer in the ways that matter most.
Money should support your life, not keep moving the finish line. Real wealth is not always loud. Sometimes it is quiet, steady, flexible, and deeply unbothered by someone else’s vacation photos.
Note: This article is based on current U.S. personal finance, household spending, inflation, debt, income, and behavioral finance research. It is for educational purposes only and should not replace personalized financial advice.