Teaching kids to save money sounds simple until you realize children are tiny, fast-moving philosophers who can turn a trip to Target into a courtroom drama. One minute you are explaining why socks count as a “need,” and the next minute your child is presenting a closing argument for a glitter-covered water bottle that costs more than your lunch. That is exactly why money lessons matter early. Saving is not just about piling up dollars in a jar. It is about patience, planning, self-control, and learning that every dollar has a job instead of wandering off to buy gummy worms and mystery slime.
If you want to raise kids who can handle money responsibly, the goal is not to turn them into tiny accountants with spreadsheets and soul-crushing lectures. The goal is to help them understand how money works in real life. They need to see where money comes from, where it goes, and why saving for tomorrow sometimes beats buying nonsense today. The good news is that you do not need a finance degree, a family trust, or a dramatic PowerPoint presentation titled Compound Interest: The Musical. You need consistency, age-appropriate tools, and a willingness to let kids practice with real choices.
This guide breaks down 20 practical ways to teach kids how to save money responsibly at any age. Some ideas work for preschoolers who still think quarters are magical. Others are better for tweens, teens, and young adults who are learning to budget, compare prices, and resist the urge to spend every cent five seconds after earning it. Use what fits your child, skip what does not, and remember that money habits are built in small moments, not one epic family lecture over pancakes.
Why Teaching Kids to Save Money Matters
Kids who learn to save do more than build a piggy bank. They learn to delay gratification, set goals, make tradeoffs, and think ahead. Those are life skills disguised as money skills. When a child decides to wait three weeks for a skateboard instead of blowing all their birthday cash in one afternoon, they are practicing discipline. When a teen compares bank accounts and notices one has fewer fees, they are practicing judgment. When a young adult learns to save part of every paycheck automatically, they are practicing responsibility.
That is why the best money lessons are practical. They work best when kids can touch the cash, see the jars, track the progress, and feel the difference between “I want this now” and “I want something bigger later.” Saving becomes real when it has a face, a purpose, and a deadline.
20 Ways to Teach Kids How to Save Money Responsibly at Any Age
1. Start embarrassingly early
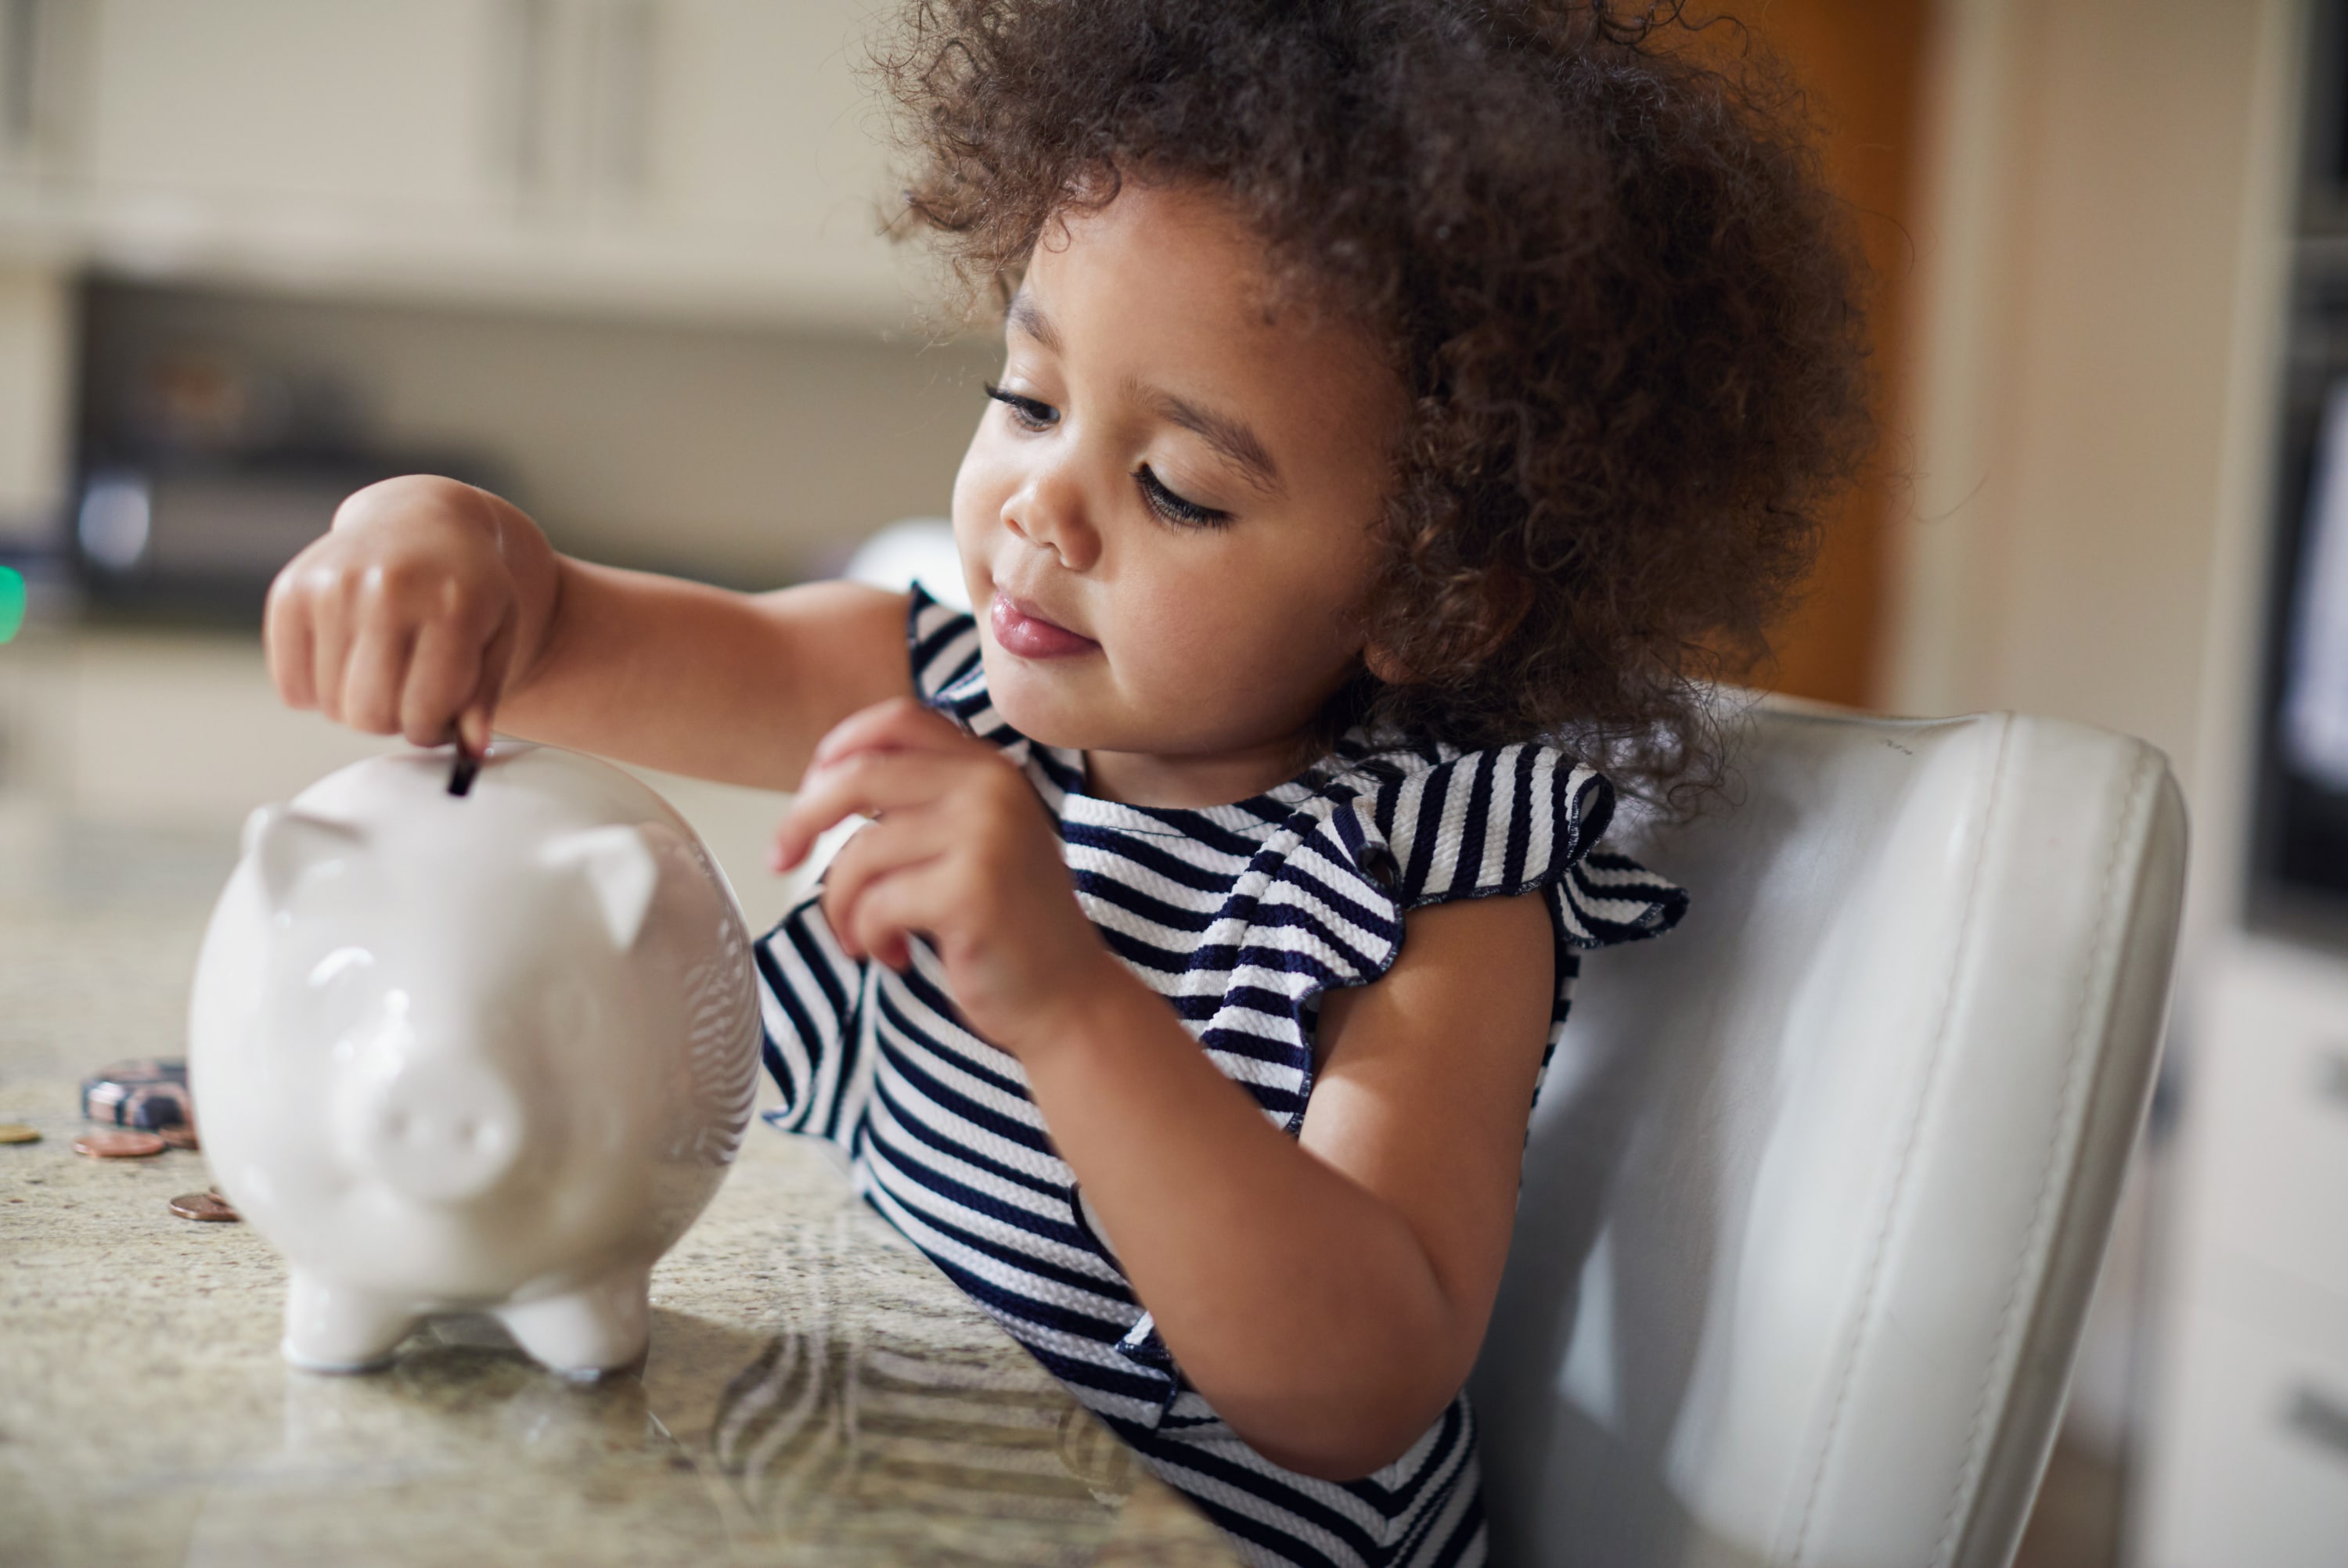
You do not have to wait until middle school to talk about money. Preschoolers can learn that money is used to buy things, that some things cost more than others, and that waiting can be part of the plan. Keep it simple. “We are saving for that toy, so not today.” That tiny sentence does a lot of heavy lifting.
2. Use clear jars instead of a mysterious piggy bank
Young kids understand what they can see. A clear jar lets them watch money grow instead of wondering whether the pig ate it. Visual progress is motivating. It turns saving from an abstract lecture into a tiny victory parade made of coins.
3. Create money buckets for save, spend, and give
One of the easiest ways to teach balance is to divide money into categories. A “save” jar teaches patience, a “spend” jar gives kids freedom, and a “give” jar helps them think beyond themselves. This system also prevents the classic childhood complaint: “I had money, and now I mysteriously do not.”
4. Teach the difference between wants and needs
This lesson may save your grocery budget and your sanity. Kids need food, shoes, and school supplies. They may passionately desire glow-in-the-dark sneakers with wings, but that is a different department. Use everyday examples and keep repeating the concept until it sticks.
5. Give an allowance with a purpose
An allowance can be a powerful teaching tool when it comes with expectations. It does not have to be huge. The point is to give kids regular opportunities to make choices. If they receive money weekly, they can learn how fast it disappears and how much easier saving becomes when they do not spend every dollar on day one.
6. Let kids earn extra money for extra work
Some families tie allowance to chores. Others separate basic family responsibilities from paid work. Either approach can work. The important part is helping kids connect effort with earnings. Extra jobs like washing the car, helping with yard work, or organizing the garage can teach that money does not float gently from the heavens.
7. Attach savings to real goals
Saving works better when kids know what they are saving for. A goal makes the process concrete. It could be a bike, concert tickets, sports gear, or a game console. Write down the cost, track progress, and celebrate milestones. Suddenly saving feels less like punishment and more like progress.
8. Make goal charts visual and fun
Kids love filling in a chart, coloring a thermometer, or adding stickers to a savings tracker. Adults call this “goal reinforcement.” Kids call it “look, I’m halfway to the LEGO set.” Same concept, fewer buzzwords.
9. Resist the urge to bail them out
If your child spends all their money on tiny plastic nonsense and then cannot afford the bigger thing they wanted, that is not a parenting failure. That is a lesson. Rescue too quickly, and the lesson disappears. Letting kids feel the sting of a bad money choice while the stakes are small is far kinder than letting them learn the same lesson later with rent.
10. Model good money habits out loud
Kids watch everything, especially the things you think they are not noticing. If you compare prices, talk through savings goals, wait for sales, or skip impulse purchases, say it out loud. “I want this, but I do not need it today.” That kind of narration teaches far more than a speech that begins with “When I was your age…”
11. Take them shopping and turn it into a lesson
Shopping is a gold mine for money education. Show them unit prices. Compare brands. Discuss sales that are actually deals and “discounts” that are mostly emotional traps wearing red stickers. Give older kids a set amount for a category and let them make choices within it.
12. Teach them to wait before buying
Impulse spending is not just an adult hobby. Kids do it too, especially when bright packaging and limited-edition claims are involved. Create a waiting rule. For smaller purchases, maybe they wait 24 hours. For bigger ones, a week. Time is wonderful at separating genuine interest from temporary obsession.
13. Introduce basic budgeting in simple language
A budget is just a plan for money. That sounds less terrifying than “budget,” which to many kids sounds like something adults say before turning off the fun. Show them that money coming in should be assigned to categories like saving, spending, sharing, and later, bills. The earlier they learn that every dollar should have a job, the better.
14. Give tweens more responsibility for small expenses
As kids get older, let them manage certain categories like snacks, school extras, small entertainment purchases, or gift shopping for friends. This teaches prioritization. When they realize buying one overpriced smoothie affects their weekend plans, the lesson lands with great emotional clarity.
15. Open a youth savings account when they are ready
At some point, kids should move beyond jars and into the real banking world. A youth savings account can help them learn deposits, balances, statements, and the simple but mighty thrill of watching money stay where they put it. It also shows that saving is not just a home activity. It is a real-world habit.
16. Help teens compare financial accounts, not just sneakers
Teenagers are old enough to start learning that not all financial products are created equal. Show them how to compare savings and checking accounts based on fees, minimums, access, convenience, and safety. This is a practical skill they will use long after they stop asking you for a ride.
17. Use debit cards and apps carefully, with guardrails
Digital money can feel imaginary, which is dangerous because imaginary money gets spent very quickly. If you give an older child or teen access to a debit card or money app, keep oversight in place. Review transactions, set limits, and talk about online spending. A button that says “Buy Now” should never be confused with “This is free and consequences are for other people.”
18. Encourage a save-first habit from every windfall
Birthday money, holiday cash, babysitting pay, lawn-mowing income, or part-time job earnings should not all go straight to spending. Teach a simple rule such as saving 10%, 20%, or another percentage first. This builds consistency and keeps saving from becoming something they only do when they “have extra,” which mysteriously never happens for most humans.
19. Add a parent match to make saving exciting
Want to make saving feel less like a vegetable and more like dessert? Match part of what your child saves. You might add $5 when they save $20 or match 50 cents on the dollar up to a set amount. This rewards effort, keeps motivation high, and introduces the basic idea that growing money can be helped by incentives.
20. Connect saving to independence, not restriction
The best message is not “saving means saying no forever.” It is “saving gives you options.” Kids are more motivated when they see saving as freedom. It means buying what matters, handling emergencies, avoiding panic, and making choices from a position of strength. That is the heart of responsible saving at any age.
How to Teach Saving by Age Group
Ages 3 to 6
Focus on visual tools, simple words, and short time horizons. Use jars, coins, pretend stores, and tiny goals. At this stage, the lesson is not compound interest. The lesson is that money can be kept for later instead of instantly vaporized on candy.
Ages 7 to 10
This is a good age for allowances, goal charts, save-spend-give systems, and early budgeting. Kids can start linking chores, work, and earnings. They can also begin learning that prices vary and that patience often gets them something better.
Ages 11 to 13
Tweens are ready for more ownership. Give them small spending categories to manage, let them compare products, and encourage them to save toward bigger personal goals. This is also a strong time to talk about advertising, peer pressure, and why “everyone has one” is not a valid financial plan.
Ages 14 and Up
Teens can handle more advanced topics like bank accounts, debit cards, budgeting apps, part-time job income, and automatic savings. The goal is to prepare them for real-world money choices before those choices become expensive.
Common Mistakes Parents Make When Teaching Kids About Saving
One mistake is making money too mysterious. Kids should hear normal, calm conversations about how choices are made. Another mistake is doing all the thinking for them. If you always decide, they never practice. A third mistake is tying every money lesson to fear. Saving should be framed as empowering, not scary. Finally, many parents are inconsistent. They create a system for two weeks, then everyone forgets about it when soccer season starts and life becomes a circus. Consistency matters more than perfection.
Family Experiences: What Teaching Kids to Save Looks Like in Real Life
In real families, money lessons rarely happen in a perfect, color-coded world. They happen in kitchens, parking lots, grocery aisles, and awkward conversations right after a child asks for something wildly unnecessary. One parent might hand a seven-year-old three jars and discover that the “spend” jar fills fast while the “save” jar looks like a lonely museum exhibit. Another family may try an allowance and realize by week two that their child spent everything on stickers, then spent the rest of the week learning the emotional consequences of sticker-based decision-making.
Many parents notice that the breakthrough moment comes when a child starts connecting money to choice. It is one thing to hear, “You should save.” It is another thing to stand in a store, hold a toy, check your own money, and realize buying it today means giving up something bigger next month. That is when saving shifts from adult advice to personal understanding.
For elementary-age kids, the most effective experiences are often physical and visible. Parents talk about using jars, envelopes, paper trackers, and little reward charts because abstract lectures do not compete well with shiny objects. Kids love seeing progress. They may not care about the concept of financial responsibility, but they absolutely care about coloring in one more square on a savings thermometer.
With tweens, the experience usually changes. This is the age when kids begin testing independence and developing stronger opinions about what is “worth it.” Some parents start giving a clothing budget for back-to-school shopping or a set amount for entertainment. At first, kids often burn through it too quickly. Then comes the surprisingly useful moment of regret. After one or two poor choices, many kids become sharper shoppers. Funny how math gets interesting when it affects snacks, hoodies, and movie money.
Teens bring a different set of experiences. Parents frequently find that teens understand money better when it becomes connected to real income. A paycheck from babysitting, tutoring, retail work, or yard work changes the tone. Money stops feeling theoretical once a teen has spent three sweaty hours earning what can disappear in ten online clicks. That is also when automatic saving starts to make sense. If part of the money moves to savings before the teen touches it, the habit forms with less drama.
Another common experience is discovering that kids learn more from calm repetition than from one giant money talk. Families who do this well often have short, regular conversations instead of big lectures. They talk while driving, shopping, paying bills, or planning a birthday purchase. Over time, children begin using the language themselves. They ask whether something is a want or a need. They compare prices. They say they are “saving up.” That is when parents realize the lesson is sticking.
The biggest real-life truth is that teaching kids to save responsibly is not about raising perfect savers. It is about raising thoughtful decision-makers. Kids will still make mistakes. They will still buy silly things. Honestly, some adults are still out here buying nonsense, so let us stay humble. But if children learn to pause, plan, save, and think ahead more often than they used to, the lesson is working.
Final Thoughts
Teaching kids how to save money responsibly is less about one magical technique and more about steady repetition. Start early, keep it practical, let them make small mistakes, and gradually give them more responsibility as they grow. Saving should feel like a useful skill, not a punishment. When children learn that money can be planned, protected, and used with intention, they gain something much bigger than a growing balance. They gain confidence.
And that is the real win. A child who knows how to save is not just preparing to buy a bike, a phone, or a first car. They are preparing to think clearly, act responsibly, and build a future with fewer panic purchases and more purposeful decisions. That is a lesson worth every jar, chart, allowance debate, and checkout-line negotiation.